
Hybridan Monthly, 5 October 2026
Market Comment: View from the Broker's Desk:
Small Caps, Big Themes: Capturing Thematic Investment Opportunities Across the Supply Chain
For small-cap investors, thematic investing is increasingly moving beyond the obvious beneficiaries. The question is no longer simply whether a company operates in defence, but whether it sits at a critical point in the supply chain created by those themes. Defence spending is rising and governments are increasingly focused on securing supplies of critical minerals. For investors, this creates an opportunity to look beyond the large-cap headline names and identify the smaller companies supplying the materials that make these themes possible.
Defence is perhaps the clearest example. The UK Government has committed to increasing defence spending to 2.5% of GDP from April 2027, representing an additional £13.4bn a year compared with the previous position. The US is also increasing spending, with its FY2026 defence budget reaching approximately $1.01tn. The obvious beneficiaries are the major defence contractors, but modern defence systems require a wide range of raw materials, including titanium, tungsten, aluminium, nickel, rare earths, graphite, copper and lightweight alloys.
Magnesium is particularly interesting. It is one of the lightest structural metals and can be used in high-strength, lightweight alloys where reducing weight can improve performance, range and payload. That makes it relevant to aerospace and defence applications. The strategic problem is supply and according to the US Geological Survey, China accounted for an estimated 88% of global primary magnesium production in 2024. Western manufacturers are therefore heavily exposed to a concentrated supply chain. As governments seek to rebuild defence industrial capacity and reduce strategic dependence on overseas suppliers, alternative sources of critical materials become increasingly important.
Panther Metals (PALM.L 185.00p £20.70m) * provides an example of the type of early-stage opportunity that can attract thematic investors. At its Dotted Lake project in Ontario, Canada, drilling has identified a 214.7-metre open-ended zone grading up to 21.7% magnesium, equivalent to 36% magnesium oxide (MgO). Other reported intersections include 129 metres at 14.4% magnesium and 94.4 metres at 17.7%. The scale and grades demonstrate why the project is potentially significant. On 18 August, Panther reported preliminary metallurgical testwork achieving 38% magnesium recovery using the Extrakt process. For investors, the attraction is therefore not simply the magnesium price, but getting exposure to a strategically important material at a time when Western supply is highly concentrated elsewhere. That is the essence of thematic investing: identifying the supply-chain bottleneck rather than simply buying the headline sector.
The nature of capital entering strategic minerals is also changing. Governments are increasingly willing to provide financing where projects are considered important to national security and supply-chain resilience. On 29 September, Panther Metals completed its registration with the U.S. Federal System for Award Management (SAM.gov), received a Unique Entity Identifier (UEI) and been issued a NATO Commercial and Government Entity (NCAGE) code through the UK Ministry of Defence, providing the identifiers required to engage directly in relevant U.S. Government procurement and funding opportunities. The registrations represent another practical step in positioning the Company within the North American critical minerals supply chain, as Panther advances engagement in relation to its Ontario, Canada project portfolio, where one opportunity already has the potential to be strategically significant to long-term North American critical mineral supply.
In August 2026, the US Department of Defense’s Office of Strategic Capital announced a conditional commitment of up to $400m in long-term debt financing for Sunrise Energy Metals Limited (ASX: SRL A$21.09 A$3.57bn) and its Syerston scandium project in Australia. Scandium is different from magnesium, but it illustrates the same theme in that it can be used in lightweight aluminium alloys for aerospace and defence applications.
Closer to home, in September 2026, Strategic Minerals (SML.L 5.9p £168.70m) secured $9.25m of funding from the U.S. Department of War for its wholly owned Cornwall Resources subsidiary to accelerate the Redmoor tungsten-copper-tin project in Cornwall through feasibility studies and towards a final investment decision. Redmoor is described as Europe’s highest-grade undeveloped tungsten resource and one of the highest-grade globally. The US funding reflects its strategic importance to developing a secure, resilient allied supply of tungsten for defence, advanced manufacturing and critical-minerals supply chains. The significance is broader than one or two financing deals. Strategic minerals are increasingly being assessed not just through commodity prices, but through national security, industrial policy and supply-chain resilience. This fundamentally creates a new source of capital for small resource companies developing strategically important assets.
The resurgence of interest in mining should not be viewed simply as a response to higher commodity prices. Investors are increasingly looking across the supply chain and asking where strategic bottlenecks will emerge. In defence, that runs from government budgets to prime contractors, components and ultimately the raw materials required to build equipment. Wars come and go, but modern warfare is increasingly characterised by high volumes of drones, missiles and autonomous systems. The economics of attrition create pressure to produce more equipment at lower cost and greater scale, sustaining demand for the materials and technologies that enable it. For small-cap investors, the opportunity may therefore lie one or two steps down the supply chain. The next generation of thematic investing may be less about owning the headline winner and more about identifying the infrastructure behind the theme.
By Niall Pearson
Company Reports: A closer look at two other stocks that have caught our eye over the last month
This month we would like to highlight developments at two gold stocks – Cora Gold and Talon Resources
Cora Gold Ltd 11.50p £91.80m (CORA.L)
| Price | Results | Top 3 Shareholders & any Director Holdings above 3% | Value Drivers |
|---|---|---|---|
| 11p-12p | Year End 31 December | Eagle Eye Asset Holdings Pte. Ltd 29.85%* | Finance in place to develop mine |
| Spread 9% | Reported 18 May | Brookstone Business Inc 20.41%** | Simple project with attractive all-in cost |
| 52-week High/Low 12.25p/5.05p | Interims to 30 June, reported 4 September | Lord Farmer 12.66% | Exploration continues |
*Eagle Eye Asset Holdings Pte. Ltd. is a Monetary Authority of Singapore registered single-family office, managing the investment portfolios of the founding & promoter family, of which Aryann Gupta (Non-Executive Director of Cora) is a family member. Eagle Eye Asset Holdings Pte. Ltd. is established as a trust, of which Aryann Gupta (Non-Executive Director of Cora) is a beneficiary. **Wholly owned & controlled by First Island Trust Company Ltd as Trustee of The Nodo Trust. Patrick Quirk, father of Paul Quirk (Non-Executive Director of Cora), is a potential beneficiary of The Nodo Trust.
Cora is a West African gold developer, whose primary focus is the development of the Sanankoro project in south Mali into an open pit oxide mine, with first production by March 2028.
Mining in the first few years will be actively helped by the fact that Sanankoro is characterised by heavily weathered ‘soft’ rock down to about 120m. This weathering is why the material is oxide (i.e. has been exposed to oxygen/rainwater/surface moisture). A September 2025 definitive feasibility study (DFS) estimated that the all-in sustaining cost at the mine would be approximately $1,721 per ounce (oz) of gold (Au) at a $4,000 Au price. The favourable economics translated to a high post-tax internal rate of return, and a rapid payback on project costs. The DFS was put together by SENET, one of the leading project management and engineering firms with strong West African experience.
Cora’s largest shareholder, Eagle Eye Asset Holdings Pte. Ltd (EEA), is a Singapore-based single-family office, and a major strategic shareholder/funding partner for an Australian-listed business called Toubani Resources. Via this involvement, EEA is backing the development of Toubani’s Kobada mine, another Au project in Mali that is open-pit, and oxide-dominant. The Kobada mine can be seen on the map below, and it is only 10km or so from Sanankoro.
EEA was the largest participant in a £15.7m fund raising that Cora undertook on 27 March, and it subsequently agreed to fund a $120m ‘gold stream’ financing package to support the development of Sanankoro through to production. The pre-production capital requirement to cover machinery and equipment, a tailings storage facility, civil works, and so on, has been put at US$124m.
In return for the funding, EEA is entitled, for the life of the mine, to purchase 30.44% of Au production from Sanankoro at a price equal to 20% of the prevailing spot price. This will reduce to 15.22% if Cora is able to replace half of the promised funding with traditional senior debt by the later of (i) 30 October 2027 and (ii) a date that is 6-months after the granting of a mining rights permit by the Malian government. EEA's appointee to Cora’s board, Mr Aryann Gupta, is a member of the family behind EEA and Head of Mergers & Acquisitions at A2MP Investments FZCO, a platform dedicated to unlocking Africa's potential in minerals and metals processing.
The project manager at Sanankoro is Lourens Steenekamp, who has over 30 years of experience with groups such as Gold Fields, Barrick Mining Corporation, Resolute Mining and Perseus Mining. This has seen him managing construction projects in Mali and the Ivory Coast. To expedite the development of Sanankoro, Cora also appointed Russell White as a Non-Executive Director on 1 September. He was described as having “over 40 years' experience in mineral processing, project delivery and mine operations, predominantly on West African gold projects.”
The front-end engineering and design process for a processing plant near the mine site is said to be progressing well. Geotechnical drilling and test excavations have been completed at the process plant and power station areas to support detailed foundation designs. An exploration camp upgrade has also been completed (new security perimeter fencing, refurbished accommodation and upgraded facilities), and final geotechnical work has begun on the 174-hectare site selected for the tailings’ storage facility. Updated technical proposals and design information is also in place for all major process areas, including crushing and transfer to milling, the rotary drum scrubber and ball mill circuit, and the carbon in leach (CIL) and elution circuits. Crushing will not take much effort as the material that will be mined – saprolite – is a naturally crumbly soft rock. CIL refers to the process of dissolving gold from the broken-down rock using cyanide leaching, and the trapping of the dissolved gold onto activated carbon. Elution is the use of a hot, pressurised mix of a solution (usually formed of caustic soda and sodium cyanide) to wash and strip the gold off the carbon. Commenting on the progress made at site, Bert Monro, Cora’s CEO said:
“This work is progressing in tandem with our resource expansion work, which has yielded highly positive initial results. The programme is targeting extensions to existing deposits and near-mine greenfield targets, with the aim of expanding the current JORC-compliant mineral resource of over one million ounces. This is setting the stage for a low-cost, high-margin, long-life mine at Sanankoro.”
The “resource expansion work” refers to a 12,000-metre drill programme, which is underway to target near-mine greenfield targets and extensions to existing deposits. This is in the belief that there is great scope to add to Sanankoro’s Maiden Resource Estimate (MRE) of just over 1.04m oz of Au (which was released by external consultants in 2024). Assay results for several holes from ‘Zone B’ of the new drilling programme have already been released, with highlights including 34m @ 6.78g/t (grams per ton) Au, 22m @ 2.24g/t, and 54m @ 1.06g/t. In total, Zone B (which will host the planned open pit mine, and which can be seen in the upper right quadrant of the map below) should account for about 40% of the drilling programme. It is a priority target due to limited deeper drilling, the sheer size of the zone, and the potential to improve continuity within the existing resource area.
Cora Gold’s Sanankoro’s project in Mali
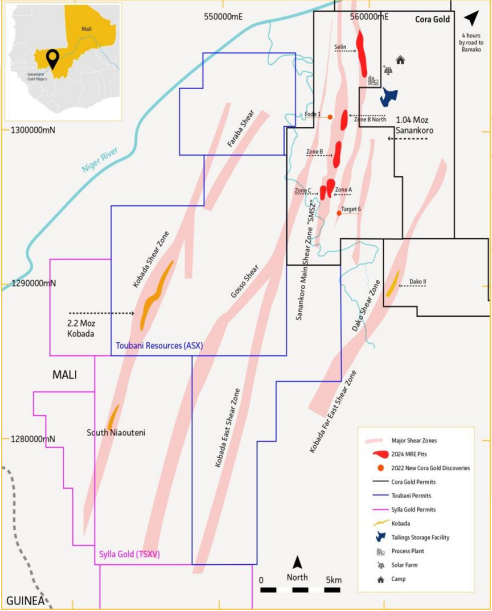
Source: Cora Gold Ltd, with the overall Sanakoro project area made up of the contiguous Bokoro II, Bokoro Est, Dako II, Kodiou & Sanankoro II permits.
Hybridan Comment: The assay results released on 7 September made it clear that gold-bearing mineralisation does extend beyond areas incorporated into the current MRE model. If additional high-grade zones can be identified, it is possible therein that Sanankoro’s planned mine life could be extended via a deeper pit/an underground development.
The drill programme at Sanankoro remains ongoing, and further assay results can be expected. The grade and intercept detail may well assist in any background senior debt discussions.
Investors in Cora will also be hoping to learn that a mining permit has been granted by the Malian authorities. The International Trade Administration estimates that Mali was the second largest gold producer in Africa in 2024. It also estimates that gold accounted for 80% of Mali’s total exports in the same year. Cora has emphasised that it continues to engage actively with the Government on its exploitation permit application and a related permit ‘reshaping exercise’ to consolidate all mining infrastructure under a single mining permit area.
Production at Sanankoro is projected to be 55,000 (k) oz in year one, and 70k oz in each of the following two years. That adds up to 195k oz over the 2028-2031; the first three years of the currently envisaged mine life. EEA, the provider of the mine’s $120m ‘gold stream’ financing package, is currently entitled to purchase 30.44% of production. The grant of a mining permit will also give the Malian State a 10% stake, but Cora’s remaining share (116,142 oz) could still amount to revenues of $464m between 2028 and 2031, if Au prices remain at c.$4,000 per oz. With the DFS pointing to a forecast all-in sustaining cost of approximately US$1,721 per oz at that gold price, we would look to highlight that the gross profits to Cora from Sanankor0 over the same three-year period could amount to as much as $323m.
As announced by the Company on 24 August 2026, Mali's Council of Ministers has approved the first interim renewal of the Sanankoro II exploration permit (which covers 84 square kilometres), and this clearly represents a positive step in the overall permitting process. The Company is in the process of renewing the Bokoro II and Kodiou exploration permits as well. As such, any potential investors are advised to keep a close eye on related news flow. We note that Cora is tightly held, with 65% of outstanding shares not in public hands.
Further, Sanankoro is due to have a solar focussed hybrid power solution which will reduce diesel usage by 40m litres over the current 10-year reserve life of the mine. The existing exploration camps all use solar power, when possible, and Cora has installed solar lights in the local village square. It has also provided domestic solar supplies for distribution amongst the local community and supported the local health centre. Elsewhere within the local community it has contributed to the salaries of teachers in the schools; financed a new water well at a community village garden; donated market garden equipment; and founded a village saving and credit association.
Talon Resources 1.43p £8.10m (TAR.L)
| Price | Results | Top 3 Shareholders & any Director Holdings above 3% | Value Drivers |
|---|---|---|---|
| 1.35p-1.5p | Year End 31 December | Ulvestone 37.94% | Highly prospective land in proven gold belt |
| Spread 11.11% | Yet to report – only admitted to AIM on 23 June 2026 | Manumit* 9.84%, | Good early channel grades |
| 52-week High/Low 3.15p/1.275p | Interims to 30 June, reported 29 September | Daniel Betts 9.70%* | AI/ML exploration support |
Source: Alpha Terminal, Shareholdings from Company website, Ulvestone has requested that 106,000,000 Consideration Shares be issued directly to Manumit and Daniel Betts in lieu of cash for consultancy services provided to Ulvestone in connection with the Eagle Lake Project
Talon’s key point of appeal is the land it has secured in Ontario. It is in the Archean Superior Province — a geological address that plays host to a plethora of existing gold mines (see below) – and this part of the province is ‘Archean’ because it was formed in the earliest period of the earth’s history. It is also ‘Superior’ because it extends across a massive 1.57m sq km. Talon’s 20 sq km block (90% owned) is in the Wabigoon sub-province, and road access sits within three kilometres of the licence boundary. There is a regional airport close by, with the closest town of Dryden known as a ‘mining town.’ The permitting framework in the whole area is also clear and understood.
Location of Talon Resource’s Eagle Lake project in Canada
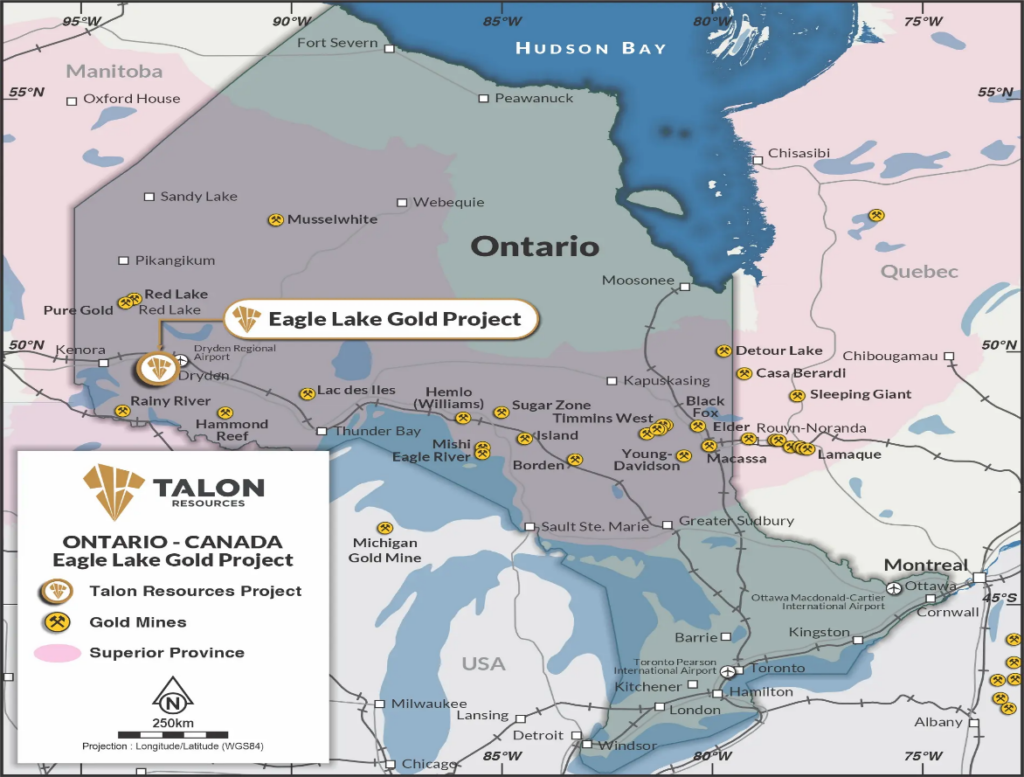
Source: Talon Resources plc
Gold found in the Archean Superior Province was generated about 2.7bn years ago during the Orogeny, a period characterised by tectonic movement and the formation of mountains. In the area, vast packages of volcanic and sedimentary rock were buried and squeezed under intense pressure. Heating these buried layers had a ‘pressure cooker’ effect, with gold-bearing hydrothermal fluids forced out in enormous quantities. The hot fluids travelled up through structural faults, and as the fluids cooled and filled fractured rock, they formed the orogenic gold-quartz veins mined at sites such as Timmins (shown in the middle of the map above) and Val d’Or.
Outside of Talon having a “good address”, it is also worth noting that the other big aspect of their appeal is a collaboration with MINML, a business founded by a group of Cambridge University earth scientists. MINML’s proprietary PRISM (Predictive Resource Intelligence & Spatial Modelling System) platform integrates geoscientific data with machine learning to map mineral prospectivity, quantify uncertainty and rank exploration targets. And via their collab with Talon, the first application was on Talon’s Eagle Lake dataset (with the prospect already being deemed a priority because surface exploration has identified 7km of strike).
In practice, this meant that MINML's model was trained on both surface samples and drill core, airborne magnetic and electromagnetic surveys, provincial geological mapping and terrain data. The model was validated against the property's existing exploration targets, and it identified 13 targets across more than 230 hectares within the 20 km² property.
MINML is backed by the UK impact investment firm Eka Ventures, and it is worth noting that their partnership with Talon is structured to support not just Eagle Lake, but also a broader strategy across the wider province. If the technology generates credible new targets beyond Eagle Lake, it is possible therein that Talon moves from being seen as a single-asset exploration play, into a ‘platform’ with multiple targets.
For now, however, the first phase of the exploration programme at Eagle Lake should add up to 1,169m of diamond drilling across four target areas. The campaign started at the East Fornieri Bay target with four holes targeting a vein array (very well-defined and stacked closely together) that Phase 1 channel sampling appears to have already intersected. Channel CH-03 returned 4.80m at 4.47 g/t Au (grams per tonne of gold), with one associated metre recording 19.10 g/t Au, while CH-01 returned 1.85m at 7.17 g/t Au on the western part of the vein set.
This was followed up by four holes at the Cedar Trench target. This area is the strongest ground identified on the property by MINML's model, and it is about 500m south of Fornieri Bay on the North-South line. The drill holes at Cedar Trench were targeting a potential vein stockwork beneath channel samples grading between 1.26 g/t Au and 21 g/t Au (with ‘stockwork’ hinting at mass tonnage potential of intersecting veins).
The drill rig was then moved to the other two targets of the initial phase – West Fornieri Bay and Moss Knoll before the first phase of the campaign completed. Assay results for all drilling will be released in batches, and the first set should be available soon. The results will be fed into the PRISM platform to inform the approach taken on the second 1,000m+ phase of the drilling programme.
Hybridan Comment: Eagle Lake has been known about for a while, and over the last 60 years, multiple operators have consistently found high-grade gold at surface. However, the total accumulated drilling on the project is twenty-six shallow holes, with no single hole drilled down past 150m. Hammon Reef (shown on map and about 35km away from Eagle Lake to the southeast) has 3m oz of reserves, and NexGold’s Goliath Complex – not shown on the map but just outside of the town of Dryden and only 45km from Eagle Lake – is a 2.9m oz gold resource. When you consider that one tenth of that find would equate to gold worth $1.2bn, the upside potential for Talon is clear. Talon was admitted to the AIM market in late June at 1.25p. Talon is currently trading at 1.43p, and this translates to a market cap of £8.10m.
In our next report on a House Stock below, we will stick with the theme of mining and Canada.
Spotlight on a house stock
Panther Metals 185.00p £20.70m (PALM.L)
Canada is a tier one mining jurisdiction, and the province of Ontario is noted for having an active mining industry across an array of different commodities. This is underscored by the fact that the Fraser Institute – which ranks global mining jurisdictions annually – has consistently named Ontario as a top five global choice. The extent of the support given to companies operating in the province was evident recently, when the Toronto Stock Exchange-listed business, Generation Mining (TSX: GENM CAD 0.55 CAD 177.80m), received $140m from Canada Growth Fund, and a further $50m from the Canada Infrastructure Bank, to complete a $1.3bn funding package for its ‘Marathon’ copper-palladium project. This is a “construction ready” open pit located about 10km north of the Ontario town of Marathon.
Panther Metals is an AIM-quoted business, and its market capitalisation of £177.80m is smaller than Generation Mining’s valuation of circa CAD391m, but investors with an interest in the sector will recognise that Panther Metals is known for having three potential projects that are all less than 100 kilometres (km) from Marathon.
The first is a tailings project (gold, silver, gallium and cobalt) at the old Winston mine in Ontario, but elsewhere within the province, it also has a potentially large VMS (volcanogenic massive sulphide) discovery called Wishbone; and an early-stage magnesium-led project called Dotted Lake.
Magnesium (Mg) is lighter than steel, a vibration-dampener, and easy to die-cast into complex shapes. It has been designated a critical mineral by both the US and Canada, and this reflects its importance across advanced manufacturing, and key strategic sectors such as aerospace and defence.
The critical metal designation helps to explain why Panther has just announced (29 September) two related updates – the completion of its registration with the United States Federal System for Award Management, and the issuance of a NATO Commercial and Government Entity code through the UK Ministry of Defence. The registrations provide Panther with the identifiers required to engage directly in US Government procurement of critical minerals (and equally importantly, related funding opportunities).Dotted Lake is an extensive 36.9 sq. km (square kilometre) project, and in March 2025, drill core assay results highlighted the discovery of a 214.7m wide open-ended zone with grades recorded of up to 21.7% magnesium, and separate 94m and 129m wide intercepts of mineralised magnesium-rich mineralisation. The Company is a way from being able to detail total contained metal, but even at this early stage, we believe that Dotted Lake could be a company maker.
Encouragingly, Panther recently revealed that ‘Phase 1’ metallurgical test work has already achieved a cumulative magnesium recovery of approximately 38%. Additional metallurgical testing (focusing in part on reagent management optimisation) will be conducted alongside an evaluation of potential project economics, supplemented by additional by-product credits.
In its past life, the old mine at Winston produced 100m lbs (pounds) of zinc, 6m lbs of copper, and 130,000 ounces (k oz) of silver between 1988 and 1998. The previous mining operation closed in February 1999 due to very low zinc prices at the time. The tailings – the finely ground ore ‘leftover’ after processing – were stockpiled in a storage facility and regarded as ‘waste’, but modern-day analysis has revealed that they contain meaningful quantities of gold, silver, gallium, and cobalt. This is the brownfield opportunity that Panther is looking to capitalise on.
Grades are bound to vary across the stored material, but the latest sampling programme pointed to gold grades of 1.32g/t (grams per ton), silver grades of up to 21.9 g/t, additional copper, zinc, and indium, plus a gallium grade of up to 122 ppm (parts per million), and a cobalt grade of up to 496ppm. The site benefits from proximity to grid power, rail links, and an all-weather road. It is also less than 200km to Thunder Bay, which is a major centre for engineering service providers. The next step is a Mineral Resource Estimate (MRE).
Ice barge used in a vibracore sampling programme on the frozen surface of the Winston tailing storage facility in February 2026
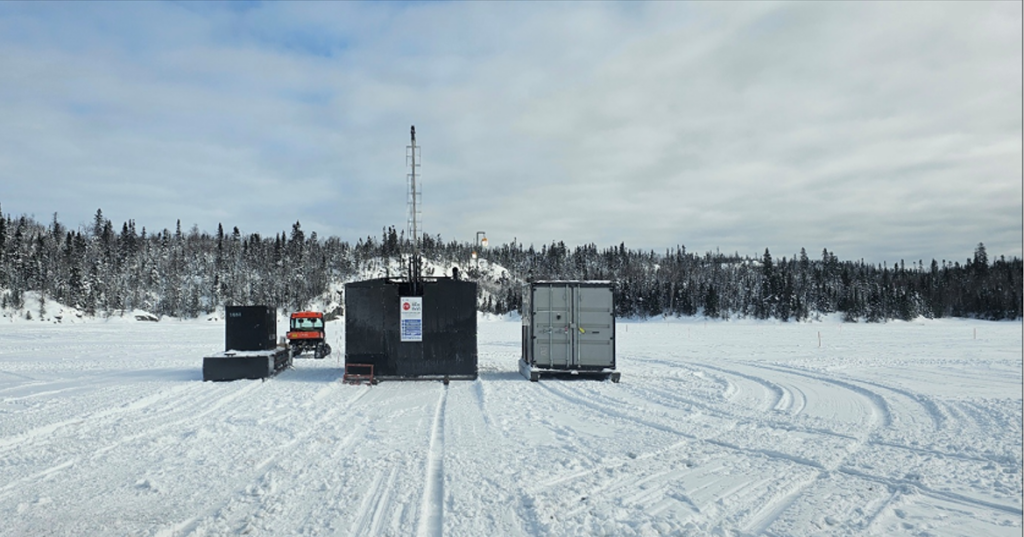
Source: Panther Metals plc
At Wishbone, the third of the projects mentioned above, it is early days as well, but historic drill information provides the tantalising prospect that Panther may have identified a large VMS system. A more up to date diamond drilling campaign has only just begun, but portable x-ray fluorescence readings have already confirmed the visual identification of copper minerals grading 8.34% copper. Laboratory assays from the programme are expected soon alongside further drilling.
Based on work undertaken to date, Panther’s management believes that Wishbone could be a VMS system comparable to Sturgeon Lake (75km or so from Wishbone in northwestern Ontario), where five historic mines produced almost 20m tonnes (mt) of zinc, copper, lead, and silver. VMS deposits were formed in sub-sea volcanic settings when hot, metal-rich hydrothermal fluids met seawater and precipitated sulphides (which are a mix of sulphur and minerals). They are typically lens-shaped and poly-metallic, with a base metal like copper or zinc seen alongside silver and gold. They can often be quite sizeable (although it is important to note that the ‘massive’ element in a VMS system refers to a high proportion of sulphide minerals rather than the dimensions of the discovery), and they can occur in clusters. They are identified via a mix of geology (volcanic host rocks that formed in a seafloor or shallow subseafloor setting), geophysics (which focuses on the physical properties of a deposit), and geochemistry (which focuses on the chemical composition of minerals in a deposit). As such, the strongest indicators of a VMS system can include hydrothermal alteration, a strong ‘conductive’ signature, and volcanic host rock ‘pathfinder-element’ anomalies in nearby soils.
Hybridan Comment: Panther’s current valuation is under-pinned by the extent of the optionality that it has across its various projects, and we await further developments with interest. Near-term catalysts include: a MRE at the Winston tailings project; additional drill results from the Wishbone project; and additional evidence that it can successfully (and profitably) extract magnesium and an array of other metals from its Dotted Lake discovery. Warrants over 0.4m shares were exercised recently, and this gave Panther an additional £0.3m of funding.
by James Follows
** Share prices, market capitalisations, and top 3 Shareholders all reported as at the close on 2 October 2026
Status of this Master Investor Purposed Newsletter, Disclaimer and Disclosures
- Disclaimer for companies mentioned with whom Hybridan does not have a corporate advisory relationship
This document has been provided as a general market commentary and is prepared by Hybridan LLP for information purposes only and should not be construed in any circumstances as investment advice; a recommendation; an offer to sell; nor any offer to buy any security or other financial instrument. Nor shall it, or the fact of its distribution, form the basis of, or be relied upon in connection with, any contract relating to such an action. The information has been provided without taking into account the investment objective, financial situation or needs of any particular person. Recipients should make their own investment decisions based upon their own financial objectives and financial resources and, if any doubt, should seek advice from an investment advisor.
As market commentary, this document is not investment research or a research recommendation for regulatory purposes as it does not constitute substantive research or analysis. It is not subject to any prohibition on dealing ahead of the dissemination of investment research although Hybridan LLP maintains related internal systems and controls in connection with such dealing.
This document should not be relied upon as being an independent or impartial view of the subject matter. The individuals who prepared this document may be involved in providing other financial services to the company or companies referenced in this document or to other companies who might be said to be competitors of the company or companies referenced in this document. As a result, both Hybridan LLP and the individual members, officers and/or employees who prepared this document may have responsibilities that conflict with the interests of the persons who receive this document. Hybridan LLP and/or connected persons may, from time to time, have positions in, make a market in and/or effect transactions in any investment or related investment mentioned herein and may provide financial services to the issuers of such investments.
This document is not intended to be an invitation or inducement to engage in investment activity. In the United Kingdom, this document is directed at and is for distribution only to persons who (i) fall within article 19(5) (persons who have professional experience in matters relating to investments) or article 49(2) (a) to (d) (high net worth companies, unincorporated associations, etc.) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005 (SI 2005/1529) (as amended) or (ii) persons who are categorised by Hybridan LLP as either a professional client or eligible counterparty (as those terms are defined in the Financial Conduct Authority’s Conduct of Business Sourcebook) (all such persons referred to in (i) and (ii) together being referred to as “relevant persons”). This document must not be acted on or relied up on by persons who are not relevant persons. For the avoidance of doubt, this document is not intended for and should not be relied upon by any person who would be classified as a retail client under the Financial Conduct Authority’s Conduct of Business Sourcebook.
The information contained in this document is based on materials and sources that are believed to be reliable; however, they have not been independently verified and are not guaranteed as being accurate. This document is not intended to be a complete statement or summary of any securities, markets, reports or developments referred to herein. The information may contain projections or other forward-looking statements regarding future events, targets or expectations. There is no assurance that such events or expectations will be achieved, and actual results may be significantly different from that shown here. The information is based on current market conditions, which will fluctuate and may be superseded by subsequent market events or for other reasons. Any and all opinions expressed are current opinions as of the date appearing on this document only. Any and all opinions expressed are subject to change without notice and Hybridan LLP is under no obligation to update the information contained herein.
References to specific securities, asset classes and financial markets are for illustrative purposes only. Past performance is no guarantee of future results. Information and opinions presented have been obtained or derived from sources which Hybridan LLP reasonably believed to be reliable however no representation or warranty, either express or implied, is made or accepted by Hybridan LLP, its members, directors, officers, employees, agents or associated undertakings in relation to the accuracy, completeness or reliability of the information in this document nor should it be relied upon as such.
To the fullest extent permitted by law, none of Hybridan LLP, its members, directors, officers, employees, agents or associated undertakings shall have any liability whatsoever for any losses arising in any way from use of all or any part of the information in this document including, for the avoidance of doubt, direct or indirect or consequential loss or damage (including lost profits).
Neither this document nor any copy of part thereof may be distributed in any other jurisdictions where its distribution may be restricted by law and persons into whose possession this document comes should inform themselves about, and observe, any such restrictions. Distribution of this report in any such other jurisdictions may constitute a violation of territorial and/or extra-territorial securities laws, whether in the United Kingdom or any other jurisdiction in any part of the world.
Hybridan LLP and/or its associated undertakings may from time-to-time provide investment advice or other services to, or solicit such business from, any of the companies referred to in this document. Accordingly, information may be available to Hybridan LLP that is not reflected in this material and Hybridan LLP may have acted upon or used the information prior to or immediately following its publication.
In addition, Hybridan LLP, the members, officers and/or employees thereof and/or any connected persons may have an interest in the securities, warrants, futures, options, derivatives or other financial instrument of any of the companies referred to in this document and may from time-to-time add or dispose of such interests.
- Disclaimer for companies mentioned with whom Hybridan has a corporate advisory relationship
Where Hybridan refers to companies that it is a retained adviser to, Hybridan marks this clearly with an *
This document should not be relied upon as being an impartial or objective assessment of the subject matter and does not constitute independent investment research for the purposes of the Conduct of Business Sourcebook (“COBS”) issued by the Financial Conduct Authority (“FCA”) to reflect the requirements of the UK retained version of Regulation 600/2014/EU (the “MIFID II Regulation”) and the UK retained version of Directive 2014/65/EU (the “MIFID II Directive”) and all rules made in connection therewith (together, known as “MIFID II”). The individuals who prepared this document may be interested in shares in the company concerned and/or other companies within its sector. As a consequence, the research (a) has not been prepared in accordance with legal requirements designed to promote the independence of investment research under MIFID II; and (b) is not subject to any prohibition on dealing ahead of the dissemination of investment research (although Hybridan does impose restrictions on personal account dealing in the run up to publishing research as set out in our Conflicts of Interest Policy).
This document has been issued by Hybridan LLP as a marketing communication for information purposes only and should not be construed in any circumstances as an offer to sell or solicitation of any offer to buy any security or other financial instrument, nor shall it, or the fact of its distribution, form the basis of, or be relied upon in connection with, any contract relating to such action. This document has no regard for the specific investment objectives, financial situation or needs of any specific entity. Hybridan LLP and/or connected persons may, from time to time, effect transactions in any investment or related investment mentioned herein and may provide financial services to the issuers of such investments. The information contained herein is based on materials and sources that we believe to be reliable, however, Hybridan LLP makes no representation or warranty, either express or implied, in relation to the accuracy, completeness or reliability of the information contained herein. Opinions expressed are our current opinions as of the date appearing on this material only. Any opinions expressed are subject to change without notice and Hybridan LLP is under no obligation to update the information contained herein. None of Hybridan LLP, its affiliates or employees shall have any liability whatsoever for any indirect or consequential loss or damage arising from any use of this document.
This document is not intended to be an invitation or inducement to engage in investment activity. In the United Kingdom, this report is directed at and is for distribution only to persons who (i) fall within article 19(1) (persons who have professional experience in matters relating to investments) or article 49(2) (a) to (d) (high net worth companies, unincorporated associations, etc) of the Financial Services and Markets Act 2000 (Financial Promotions) Order 2005 (SI 2005/1529) (as amended) or (ii) persons who are categorised by Hybridan LLP as either a professional client or eligible counterparty (as those terms are defined in COBS (issued by the FCA) (all such persons together being referred to as “relevant persons”). This report must not be acted on or relied upon by persons in the United Kingdom who are not relevant persons.
Neither this report, nor any copy or part thereof may be distributed in any other jurisdictions where its distribution may be restricted by law and persons into whose possession this report comes should inform him or herself about and observe any such restrictions. Distribution of this report in any such other jurisdictions may constitute a violation of securities laws in the United Kingdom, the United States (or any part thereof) or any other jurisdiction in any other part of the world.
The methodology and underlying assumptions used to either evaluate a financial instrument or an issuer shall, where relevant, be included (with information as to where any more detailed information can be found) in the substance of this note.
Investments in general involve some degree of risk, including the risk of capital loss. The services, securities and investments discussed in this document may not be available to or suitable for all investors. Investors should make their own investment decisions based upon their own financial objectives and financial resources and, if in any doubt, should seek advice from an investment advisor. Past performance is not necessarily a guide to future performance and an investor may not get back the amount originally invested. Where investment is made in currencies other than the investor’s base currency, movements in exchange rates will have an effect on the value, either favourable or unfavourable. Levels and bases for taxation may change. When Hybridan LLP comments on AIM or AQSE Exchange shares investors should be aware that because the rules for those markets are less demanding than the Official List of the London Stock Exchange the risks are higher. Furthermore, the marketability of these shares is often restricted.
Hybridan LLP is authorised and regulated by the FCA and is a member of the London Stock Exchange.
Issuers may be permitted to review investment analysts’ investment research prior to publication for review of factual accuracy only – all opinions expressed are our own. Investment research prepared by Hybridan LLP is monitored to ensure that it is only provided to relevant persons. Research prepared by Hybridan LLP is not intended to be received and/or used by any person who is categorised as a retail client under COBS.
Investment analyst certification: All research is issued under the regulatory oversight of Hybridan LLP. Each investment analyst of Hybridan LLP whose name appears as the author of this research hereby certifies that the opinions expressed in such research accurately reflect the investment analyst’s personal and objective views about any and all of the companies or the Company discussed herein that are within such investment analyst’s coverage universe.
The investment analyst who is responsible for the preparation of any commentary on companies that Hybridan advises is Jonathan (Jon) Levinson, who is an employee of Hybridan.
Conflicts of Interest: Hybridan LLP is involved in providing other financial services to companies it includes in this note that it is a retained adviser to and, as a result, Hybridan LLP may have responsibilities to the Company which conflict with the interests of the persons who receive this document.
Hybridan LLP and/or its associated companies may from time-to-time provide investment advice or other services to, or solicit such business from, any of the companies referred to in this document. Accordingly, information may be available to Hybridan LLP that is not reflected in this material and Hybridan LLP may have acted upon or used the information prior to or immediately following its publication.
Hybridan, its partners, officers or employees or any connected persons may at the time of publication have an interest in the equity of the Company through the holding of warrants, securities, futures, options, derivatives, and any other financial instrument of any of the companies referred to in this document. Hybridan at the time of publication currently has no interest of this nature in the Company discussed herein. If exercised such interest would not be required to be notified as it would comprise less than 3% of the Company’s issued share capital. Hybridan reserves the right to increase or dispose of this interest and/or the underlying shares resulting from exercise, without further notice. Any disposal or acquisition of warrants or shares will be undertaken under the FCA Disclosure Guidance and Transparency Rules Sourcebook.
No recommendations: In line with our conflicts of interest policy Hybridan LLP does not produce “buy” or “sell” recommendations or publish target prices on companies who are corporate clients of Hybridan LLP.
MIFID II status of Hybridan LLP research: The cost of production of our corporate research is met by retainers from our corporate broking clients. In addition, from time to time we issue further communications as market commentary (such as our daily newsletter), which we consider to constitute a minor non-monetary benefit which is capable of enhancing the quality of service provided by Hybridan LLP and which is of a scale and nature which could not be judged to impair the duty of Hybridan LLP to act in the best interest of its client falling within article 24(7)(b) of the MIFID II Regulation.
Unless otherwise stated, Hybridan LLP owns the intellectual property rights and any other rights in this document. This document may not be copied, redistributed, resent, forwarded, disclosed or duplicated in any form or by any means, whether in whole or in part other than with the prior written consent of Hybridan LLP.
Hybridan LLP is a limited liability partnership registered in England and Wales, registered number OC325178, and is authorised and regulated by the Financial Conduct Authority and is a member of the London Stock Exchange. Any reference to a partner in relation to Hybridan LLP is to a member of Hybridan LLP or an employee with equivalent standing and qualifications. A list of the members of Hybridan LLP is available for inspection at the registered office, 2 Jardine House, The Harrovian Business Village, Bessborough Road, Harrow, Middlesex HA1 3EX.
This document should be directed at and is for distribution only to persons who (i) fall within article 19(5) (persons who have professional experience in matters relating to investments) or article 49(2) (a) to (d) (high net worth companies, unincorporated associations, etc.) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005 (SI 2005/1529) (as amended) or (ii) persons who are categorised as either a professional client or eligible counterparty (as those terms are defined in the Financial Conduct Authority’s Conduct of Business Sourcebook) (all such persons referred to in (i) and (ii) together being referred to as “relevant persons”). This document must not be acted on or relied up on by persons who are not relevant persons. For the avoidance of doubt, this document is not intended for and should not be relied upon by any person who would be classified as a retail client under the Financial Conduct Authority’s Conduct of Business Sourcebook. A full disclaimer and set of disclosures are made at the end of this report.